

Annual income reporting becomes harder when salary records, bonuses, employee benefits, and staff changes sit in different systems. Your HR team may have the employee details, Finance may hold payment records, and an external adviser may manage share awards.
Singapore’s Auto Inclusion Scheme (AIS) gives employers an electronic route to report employment income to the Inland Revenue Authority of Singapore (IRAS). IRAS then includes that information in employees’ tax returns.
For your business, the practical task is to bring those records together, check them, and submit accurate information on time. This guide explains eligibility, reporting requirements, submission methods, and a workflow you can use to prepare.
What Is the Auto Inclusion Scheme?
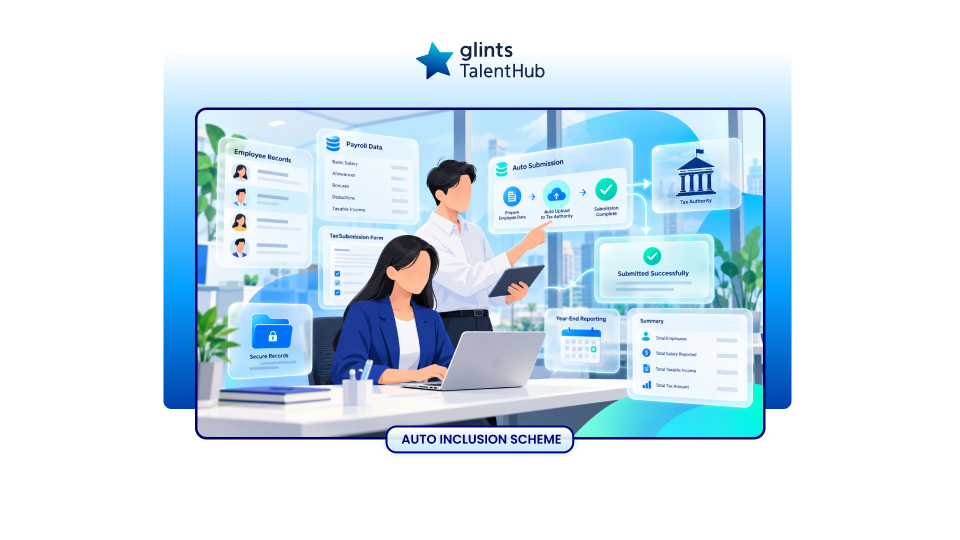
The Auto Inclusion Scheme is an IRAS arrangement under which employers submit employment income information electronically. The submitted information is automatically included in employees’ income tax returns.
This reduces the information employees need to enter themselves. Your payroll team still needs to prepare and validate the underlying records. The word “auto” describes how IRAS includes the submitted information in tax returns; it does not mean your annual payroll reporting happens without employer action.
For example, if employee details are correct but a bonus is missing from your reporting file, the electronic submission process will not resolve that omission. A reliable payroll process helps you identify gaps before submission.
Who Must Participate in AIS?
Employers with five or more employees must participate. Participation is also compulsory for employers served with a notice to file employment income electronically and employers covered by the continuing registration requirement. Smaller employers may join voluntarily. Once registered, annual participation continues even if headcount subsequently falls below five.
Count Employees Across the Reporting Year
IRAS uses the total number of employees for the year, including people who left during that year. Avoid relying only on your December headcount. For Year of Assesment (YA) 2027, the relevant period is 1 January to 31 December 2026.
As a practical check, compare your active employee list with your joiner and leaver records before deciding whether registration is required.
What is the AIS Submission Deadline?
AIS employers must submit employment income information electronically by 1 March of the following year. Therefore, the deadline for reporting income derived in 2026 is 1 March 2027, for YA 2027. IRAS states that late submission may lead to a fine of up to S$5,000.
Set an internal completion date earlier than the statutory deadline. Leave time for missing information, rejected records, and final approval.
Include annual income reporting in your Singapore payroll compliance checklist so your team can track it alongside monthly payroll obligations.
AIS vs IR8A: What Is the Difference?
AIS is the electronic reporting arrangement. Form IR8A sets out an employee’s annual employment income information. The two work together.
Employers under AIS submit the relevant information electronically and do not need to issue hardcopy IR8A forms or applicable appendices to employees. Employers outside AIS must provide employees with Form IR8A and applicable appendices by 1 March of the following year. They do not routinely send those hardcopy forms to IRAS.
Preparing a PDF or printed IR8A alone therefore does not complete an AIS employer’s electronic reporting obligation.
Which Employees Should Be Included?
IRAS reporting categories cover full time and part time resident employees, relevant nonresident employees, directors, board members receiving fees, pensioners, and former employees receiving reportable income.
Important exceptions and special cases include:
- Tax clearance cases: Do not duplicate income already assessed through Form IR21. Additional unreported income for those employees should be reported through an additional IR21.
- Business owners: Sole proprietor drawings and partners’ business income are excluded. A salaried partner working under an employment contract is treated differently and may require AIS reporting.
- Nonresident directors: AIS reporting is not required where a nonresident director receives directors’ fees only.
- Rehired employees: Consolidate income into one record when an employee leaves and rejoins within the same year.
For teams operating across borders, check the circumstances of each overseas assignment rather than treating every overseas payment identically.
What Information Do Employers Need to Prepare?
What Information Do Employers Need to Prepare?
The reporting framework includes:
- Form IR8A: Annual employment income information.
- Appendix 8A: Applicable benefits provided in kind.
- Appendix 8B: Relevant gains from employee stock option or share ownership plans.
Build a working pack that brings together employee identifiers, employment dates, salary totals, bonuses, commissions, allowances, benefits, share plan information, and applicable deductions. Use the current IRAS instructions to determine the treatment and reporting field for each item.
Understanding gross salary helps your team reconcile cash earnings before checking the separate tax treatment of benefits and other reportable items.
Keep payment evidence and calculation notes alongside your working file. A reviewer should be able to trace a reported amount back to the payroll record or supporting schedule without reconstructing the calculation.
How to Register for AIS
IRAS now makes registration available throughout the year. As of 23 October 2026, registration for YA 2027 is open until 1 March 2027. Employers should register only after hiring at least one employee.
Register through the AIS registration service on myTax Portal and retain the acknowledgement. Check that you select the intended YA.
Assign a named person to own registration and annual reporting so the task remains visible when responsibilities change.
How to Submit AIS Records
IRAS supports submission through payroll software integrated with its AIS API service or through the Submit Employment Income Records digital service on myTax Portal. Confirm your chosen software supports the relevant YA.
A practical submission workflow is:
- Confirm the reporting population. Match payroll records against joiners, leavers, directors, and other relevant recipients.
- Reconcile annual amounts. Investigate differences between payroll totals, payment records, and supporting schedules.
- Review special items. Give benefits, share awards, overseas assignments, and tax clearance cases a separate review.
- Check access. Confirm the person handling submission has the required authorisation before the final week.
- Validate and submit. Resolve errors through your chosen submission route.
- Check status. Retain the acknowledgement and verify the submission status in myTax Portal.
If you work with a payroll provider, agree who prepares, reviews, approves, and submits the information. Make the handover dates explicit.
How to Correct an AIS Submission
IRAS distinguishes between two correction methods:
- Revision submission: Replaces the previous record using the full, correct amounts for all relevant fields. IRAS recommends this method.
- Amendment submission: Adjusts the previous amounts using only the difference between what was reported and the correct total.
For example, suppose a bonus was reported as S$4,000 but should have been S$5,000. A revision uses the complete corrected record, including the S$5,000 bonus. An amendment reports the S$1,000 increase in the affected field.
These are different methods. Check which one you are using before entering figures. Omitted employees and incorrect identity numbers also require the appropriate correction process. Follow the current IRAS guidance for the specific error.
Do Employees Still Need to File a Tax Return?
Employees must file if IRAS instructs them to do so, even when their employer participates in AIS. They can check their submitted employment income information on myTax Portal from 1 March of the following year.
After submission, tell employees when to check their information and who to contact about discrepancies. Explain that income already included through AIS should not be entered again as additional employment income.
A short employee communication can prevent confusion:
Your employment income information has been submitted to IRAS through AIS. Please check the information in myTax Portal against your records and contact HR if you notice a discrepancy. Follow any filing instructions you receive from IRAS.
Common AIS Mistakes to Avoid
1. Checking Only Current Employees
Use your annual payroll population when preparing the reporting list. An active employee export can leave out someone who departed earlier in the year.
2. Leaving Benefits Until the Final Review
Collect benefit and share plan information alongside salary records. Give each schedule an owner and a delivery date.
3. Treating Successful Transmission as a Full Accuracy Check
Technical acceptance and financial accuracy are separate checks. Review the employee population and reported amounts before approving the file.
4. Assuming Your Provider Handles Every Step
Your service agreement should identify the submission scope, required inputs, approval process, and responsibility for corrections. Confirm those details before the reporting cycle begins.
If you are considering payroll outsourcing, confirm which reporting activities are included and what your team must review and approve.
Make Annual Reporting Easier With Better Payroll Records
AIS preparation is more manageable when your monthly payroll records are consistent and your reporting responsibilities are clear. Regular reconciliation reduces the amount of investigation your team needs to complete near the deadline.
Glints TalentHub’s payroll service supports salary calculations, statutory contributions, tax support, and payroll reporting. If your team needs help coordinating payroll administration, discuss your reporting requirements and confirm the scope of support for your business.