

A salary offer tells you what an employee earns, but it does not always tell you what they will receive in their bank account or what your business will spend to employ them.
Gross salary is the starting point for understanding those differences. It shows an employee’s earnings before deductions, helping you communicate compensation clearly and plan payroll.
This guide explains what gross salary means, what it can include, how to calculate it, and what employers should consider when hiring across Southeast Asia.
What is Gross Salary?
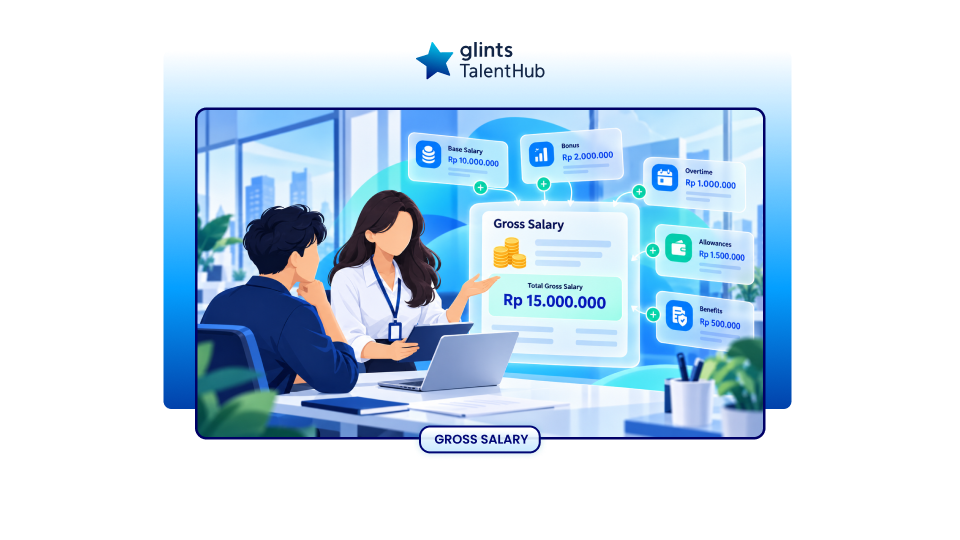
Gross salary is an employee’s earnings before deductions, such as employee social security contributions, pension contributions, and income tax withheld through payroll where applicable.
For a salaried employee, an offer may state a fixed monthly or annual gross salary. Actual gross earnings for a particular pay period may also include additional payments, such as commission or a bonus.
For example, an employee who earns a monthly basic salary of USD 2,000 and a fixed cash allowance of USD 200 has monthly gross earnings of USD 2,200 before deductions, assuming there are no other earnings or adjustments.
A salary quoted in an offer, total gross earnings on a payslip, and a legally defined salary calculation base can refer to different amounts. Always specify the period and components included.
Singapore illustrates why this matters. Its Ministry of Manpower uses a specific “gross rate of pay” definition for certain statutory calculations. That definition excludes overtime, bonuses, annual wage supplements, and travel, food, and housing allowances. Employers should therefore check the required calculation base rather than automatically using total gross earnings. mom.gov.sg
What Does Gross Salary Include?
For general payroll purposes, gross earnings can include the following cash payments when they are earned or payable for the relevant period.
| Component | What it means |
|---|---|
| Basic salary | The employee’s agreed core pay |
| Cash allowances | Payments such as fixed transport or housing allowances, depending on the relevant payroll definition |
| Overtime pay | Additional pay for eligible work beyond normal hours |
| Commission | Earnings based on sales or another agreed performance measure |
| Bonuses | Contractual or discretionary payments included when payable |
| Other cash earnings | Applicable shift payments, incentives, or other remuneration |
Not every employee receives every component. Gross earnings may remain constant each month or change with overtime, commission, bonuses, and adjustments.
Keep expense reimbursements separate from salary earnings. Repaying an employee for a documented business expense differs from providing a fixed allowance, and the two arrangements may receive different tax treatment.
Employer contributions and noncash benefits also need separate attention. A benefit can be taxable without being part of the employee’s gross cash salary. For example, Singapore’s tax authority distinguishes taxable and exempt employment benefits according to the applicable rules. Tax Principles and Flexible Benefits
Gross Salary vs Basic Salary vs Net Salary
These terms describe different stages of an employee’s pay calculation.
| Term | Meaning | Illustrative monthly amount |
|---|---|---|
| Basic salary | Core agreed pay before additional earnings | USD 2,000 |
| Gross earnings | Basic salary plus applicable additional earnings before deductions | USD 2,500 |
| Net salary | Amount remaining after applicable payroll deductions | USD 2,150 |
| Total employer cost | Gross earnings plus employer contributions and other employment costs | More than gross earnings when additional costs apply |
In this example, the employee receives USD 500 in additional earnings and has USD 350 in deductions. These figures are illustrative and do not represent statutory rates.
Basic salary and gross salary can be equal if there are no additional earnings. Gross salary and net salary can also be equal if no payroll deductions apply.
How to Calculate Gross Salary
Start with the employee’s agreed pay for the relevant period, then add applicable earnings.
Gross earnings = Basic pay + Cash allowances + Overtime pay + Commission + Bonuses + Other applicable cash earnings
Use only the components payable for that period. A potential annual bonus should not automatically appear in every month’s gross earnings.
Monthly gross salary example
Suppose an employee has the following earnings.
| Earnings component | Amount |
|---|---|
| Basic salary | USD 2,000 |
| Fixed cash allowance | USD 200 |
| Commission | USD 300 |
| Total gross earnings | USD 2,500 |
The calculation is:
USD 2,000 + USD 200 + USD 300 = USD 2,500
If the commission changes next month, gross earnings will change even if basic salary stays the same.
Annual gross salary example
An employee receives a fixed gross monthly salary of USD 2,500 for 12 months.
Annual fixed gross salary = USD 2,500 × 12 = USD 30,000
If the employee also earns a bonus of USD 2,500 that year, annual gross cash earnings become USD 32,500.
When comparing offers, distinguish guaranteed annual pay from potential variable earnings. Check whether any additional annual payment is required by local law or the employment contract.
Hourly gross pay example
An employee works 160 regular hours at USD 10 per hour.
Regular gross pay = 160 × USD 10 = USD 1,600
If the employee also earns USD 150 in eligible overtime pay, total gross pay is USD 1,750 before deductions.
Calculate overtime using the applicable local rules, employee eligibility, and required pay base.
How to Calculate Net Salary From Gross Salary
Net salary is the amount left after applicable employee deductions.
Net salary = Gross earnings less applicable employee deductions
Using the USD 2,500 gross earnings example:
| Payroll item | Amount |
|---|---|
| Gross earnings | USD 2,500 |
| Illustrative employee contributions | USD 150 |
| Illustrative tax withholding | USD 200 |
| Net salary | USD 2,150 |
The deductions are hypothetical and do not represent any country’s rates.
There is no universal percentage for converting gross salary to net salary. The result depends on the country, employee circumstances, contribution rules, and authorised deductions.
Income tax is not deducted through regular payroll in every situation. Where employees pay it separately, the amount received through payroll may still need to cover a later tax bill.
Is gross salary the same as taxable income?
Gross salary and taxable income are related, but they are not interchangeable.
Gross cash earnings describe pay before deductions. Taxable employment income follows the relevant tax rules and may include taxable noncash benefits or exclude certain exempt payments. Reliefs and deductions may then affect the amount ultimately subject to tax.
For example, Singapore’s Inland Revenue Authority explains that employment gains are generally taxable unless an exemption or administrative concession applies. A benefit’s tax treatment therefore needs to be checked rather than inferred from its label in an offer. iras.gov.sg
For payroll, keep separate records for cash earnings, taxable benefits, exempt items, and the bases used for statutory contributions.
Why gross salary is not your total hiring cost
Gross salary helps you understand an employee’s compensation, but it is only one part of your hiring budget.
Depending on the country and employment arrangement, your business may also pay employer statutory contributions, insurance, benefits, additional annual payments, equipment costs, recruitment fees, or employment service fees.
Total employer cost = Gross cash earnings + Employer contributions + Benefits and other applicable employment costs
Avoid double counting. If an annual bonus is already included in your gross earnings forecast, do not add it again as a separate employment cost.
For regional hiring, compare costs over the same annual period. A monthly salary figure alone can hide differences in required payments and employer obligations.
How to communicate gross salary clearly
State the currency and pay period
Write “USD 30,000 annual gross salary, paid in 12 equal monthly instalments” rather than “salary of 30,000.”
For cross border arrangements, clarify the payroll currency and any agreed currency conversion method.
Separate fixed and variable pay
Identify basic salary, fixed allowances, commission, and bonuses separately. Explain whether variable payments are guaranteed, conditional, or discretionary.
This helps candidates understand the amount they can rely on and the earnings that depend on performance or other conditions.
Explain deductions with clear assumptions
Share an illustrative net pay calculation where useful. State the assumptions and explain which employee circumstances could change the result.
A commitment to a particular net salary may require a different compensation calculation and change employer costs.
Provide a clear payslip breakdown
Show earnings, deductions, and net pay so employees can follow the calculation.
Singapore’s itemised payslip requirements provide one example. They distinguish basic salary, allowances, additional payments, deductions, overtime information, and net salary. Apply the requirements of the employee’s actual employment location.
Plan Salary and Payroll With Local Context
Clear salary calculations help you set accurate budgets and give employees a better understanding of their pay.
Start by defining the salary components, calculate earnings for the correct period, and apply local rules for deductions and employer obligations.
If you are hiring across Southeast Asia, Glints TalentHub can support your recruitment and employment needs, including onboarding, payroll, and local compliance. Explore Glints Payroll Service to find the service that fits your team.